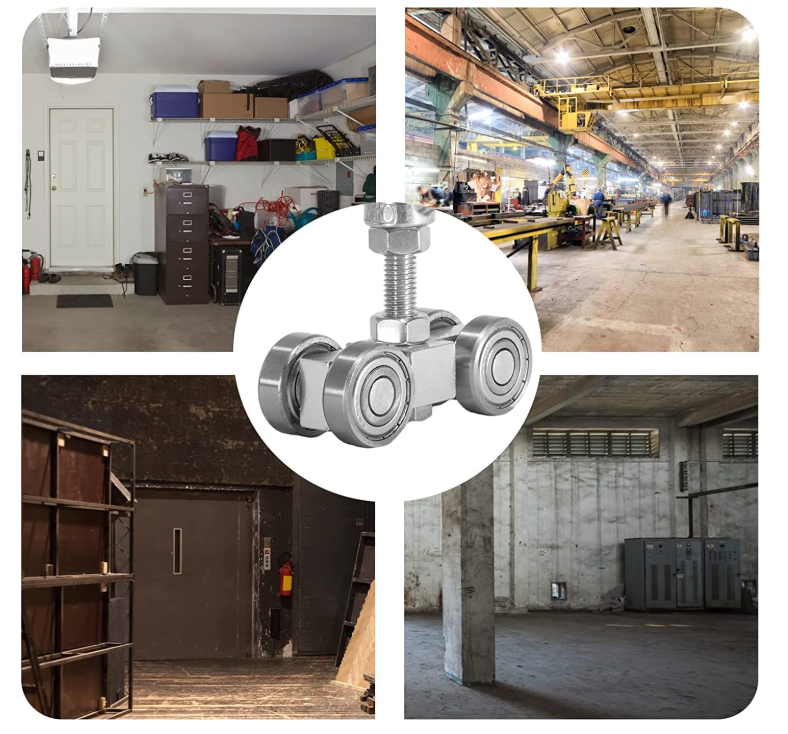
The roller is the least visible part of any sliding door system — and the one that decides whether the system works.
A sliding panel can be specified with premium aluminum profiles, triple glazing and a thermally broken frame, but if the rollers cannot carry the sash smoothly for a decade, the installation fails in the eyes of the building owner. That single fact explains why rollers and the sliding hardware around them are attracting attention out of proportion to their size — and why the segment is growing at a pace that mirrors the broader fenestration market.
The market size
The global sliding door hardware market — the category that includes rollers, tracks, hangers and their fittings — is valued at approximately
2.72 billion in 2026 and is projected to reach 3.81 billion by 2035, a compound annual growth rate of 3.9%, according to Business Research Insights. A narrower estimate from Growth Market Reports puts the sliding door roller segment on a 6.1% C A G R through 2033, reflecting the fact that rollers are a consumable, replacement-driven sub-segment that keeps moving even when new construction slows.
The parent category is larger and faster. The global market for hardware products for doors and windows — more than 250 standardized product categories spanning hinges, locks, handles, sliding systems, closers and smart access devices — was sized at
29.63 billion in 2026 and is expected to reach 52.34 billion by 2035 at a 6.6% CAGR, with more than 60% of demand tied to new construction and roughly 40% to renovation, according to Business Research Insights. A wider estimate from Mark Wide Research values the door and window hardware market at
78.4 billion in 2026,growing to 140.54 billion by 2035 at 6.70% annually.
Upstream of all of it sits the material trend: aluminum doors and windows were valued at
78.6 billion in 2026 and are projected to expand to 142.09 billion by 2035 at a 6.80% CAGR, with commercial high-rise construction accelerating the adoption of specification-grade aluminum fenestration and demand concentrating in China, India and the United States, according to Mark Wide Research.
What is actually driving demand
Three forces show up repeatedly in the market data — and they map directly onto how rollers are being redesigned.
Space-saving design. Rising demand for modern, space-saving residential layouts accounts for roughly 35% of growth in sliding door hardware, per Business Research Insights. As floor area per dwelling shrinks in dense urban markets, sliding panels replace swing doors — and every sliding panel needs a roller set, a track and hangers.
Automation and smart buildings. The integration of automated sliding door systems in smart homes and commercial spaces contributes about 20% of segment growth. Automated doors are harder on hardware: they cycle far more often than manual doors, they cannot rely on a user intuitively slowing a panel before it hits the stop, and they are expected to fail quietly rather than loudly. That pushes rollers toward larger load margins, sealed bearings and tighter flatness tolerances on the track.
Energy codes and retrofit. Thermal break regulations in the European Union and North America are reshaping compliance requirements across fenestration products, and residential retrofit activity across North America and Western Europe is accelerating replacement cycles for aging window and door systems, according to Mark Wide Research. Retrofit is where rollers matter most commercially: replacing a failed roller is often the difference between re-glazing a sliding wall and replacing the whole unit.
The constraint nobody escapes
Against that growth, the data also names the brake. The high initial cost of installation and maintenance affects roughly 25% of potential market expansion in sliding door hardware — the largest single restraint identified in the 2026 assessment. In practice, this is the cost of getting it wrong: a roller that wears unevenly, a track that is out of tolerance, or a hanger that requires a specialist crew to adjust. Every one of those failures is paid for twice — once at installation and again at the first service call.
That is why the more interesting engineering work in 2026 is not in making rollers cheaper, but in making them predictable. The specification conversation has shifted from “what does the roller cost” to “what does the system cost over its service life,” and the answers come from test data rather than catalog claims.
How the component is changing
Four design directions dominate current product development:
- Material substitution. Stainless steel ball-bearing wheels for heavy commercial sashes, engineering plastics (POM, nylon) for residential panels where quiet operation matters more than absolute load. The choice is a trade-off between acoustic performance, corrosion resistance and cost.
- Sealed and lubricated-for-life bearings. Automated and high-traffic doors make re-lubrication practically impossible, so sealed assemblies with specified cycle ratings are replacing open bearings.
- Corrosion specification. Coastal and humid-climate projects — a growing share of demand in South and Southeast Asia, the Gulf and Latin America — are moving to 304 and 316 stainless rollers as standard rather than option.
- Adjustability. Height-adjustable hangers let installers compensate for real-world slab and ceiling tolerances on site, which reduces the installation cost that the market data flags as the main restraint.
What buyers should ask for
For developers, fabricators and importers comparing roller suppliers in 2026, the durable questions are consistent:
- Cycle-life test data — not a claim, but a reported figure with the test method named.
- Load rating per wheel, matched to the actual sash weight plus a margin that accounts for wind load on exterior panels.
- Material and coating specification — including salt-spray hours for coastal projects.
- Adjustment range — the millimeter range of height adjustment available on site.
- Traceability — batch-level material certificates, which increasingly appear in tender documents alongside the hardware schedule.
The outlook
Through 2035, the arithmetic is straight for ward: sliding systems are taking share in residential and commercial openings, automated systems are adding cycles, and retrofit demand is creating a steady replacement market for rollers specifically. The manufacturers that treat the roller as a documented, tested component — rather than an accessory bundled with a track — are the ones positioned to hold specification share in that market.
For producers like Shanghai Qinkai Industrial Co., Ltd., a Chinese manufacturer of steel and hardware components that supplies both infrastructure and building products, the same logic applies: the component with the smallest part number often carries the largest share of the warranty risk.
Post time: Sep-17-2026